How a 'Chronically Ill' Exception Can Save Inherited IRA Taxes
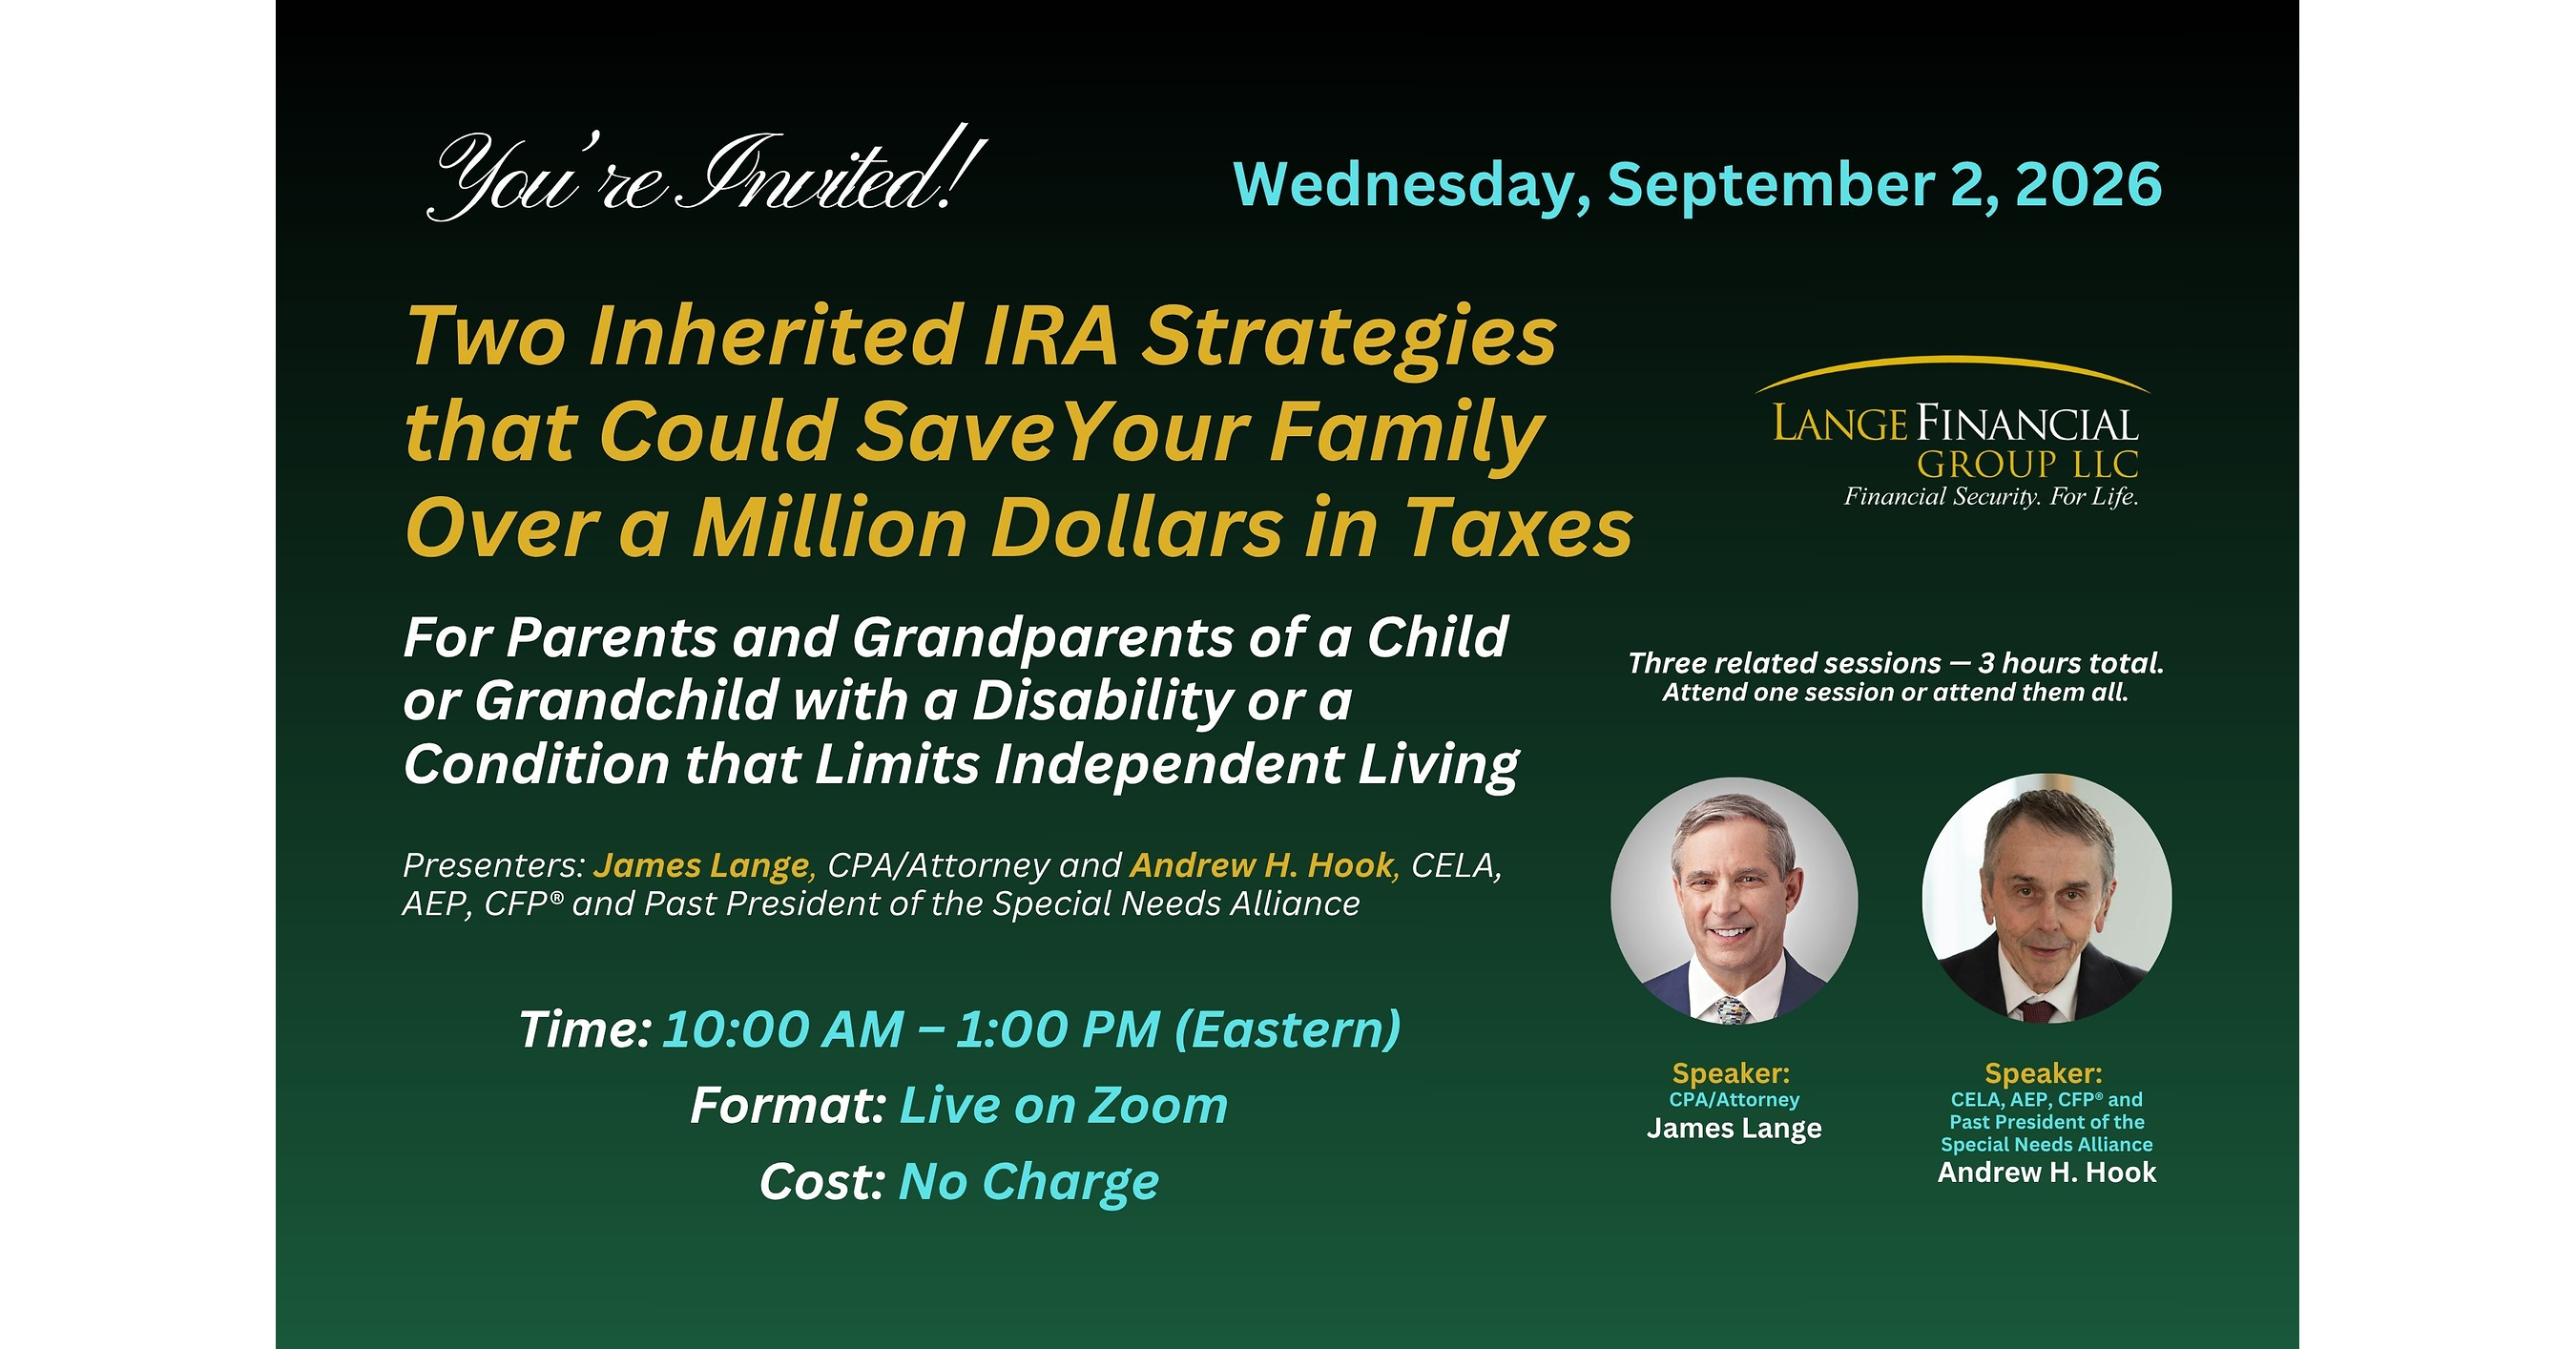
A free Sept. 2 webinar explains the chronically ill EDB exception that can preserve inherited IRA lifetime payouts for beneficiaries without SSI or SSDI.
Lange Financial Group will host a free webinar on Sept. 2 for families with children or grandchildren who do not receive SSI or SSDI. Some of those beneficiaries may still be able to stretch inherited IRA distributions over a lifetime under a little-used exception in federal tax law, the firm said.
James Lange, a CPA and attorney, and Andrew H. Hook, a certified elder law attorney of counsel to Hook Law Center in Virginia Beach, Virginia, will present "Two Inherited IRA Strategies That Could Save Your Family Over a Million Dollars in Taxes" live on Zoom from 10 a.m. to 1 p.m. Eastern.
The program centers on the chronically ill exception in Internal Revenue Code Section 7702B(c)(2). Beneficiaries who meet it can be treated as eligible designated beneficiaries, or EDBs, and take inherited IRA distributions over their life expectancy. EDB status keeps the account on life-expectancy distributions instead of the SECURE Act's general 10-year distribution rule.
EDB status does not require a disability determination from the Social Security Administration. The pathway also imposes no Social Security earnings test. Certification does not have to come from a physician; a registered professional nurse or licensed social worker can provide it. A beneficiary may work or function independently in parts of daily life and still qualify if the statutory requirements are met, the organizers said.
Hook, whose firm has worked through the chronically ill EDB certification process for clients, said the main obstacle to wider use of the pathway is lack of awareness.
"The chronically ill pathway is real, it is workable, and it is underutilized," Hook said.
In Hook's practice, the most common qualifying path has been the severe cognitive impairment and substantial supervision test, with beneficiaries including people with autism spectrum disorder, traumatic brain injury, intellectual disability and early-onset dementia.
Lange's family planning produced the case study featured in the program. After his father-in-law died, advance beneficiary and disclaimer planning allowed his wife to disclaim a $500,000 share of the inherited IRA into a special needs trust for their daughter, Erica, who qualifies as a disabled EDB. Lange projects the strategy will leave Erica about $1.178 million better off over her lifetime, measured in today's dollars.
"What few families realize is that this opportunity is not limited to beneficiaries who qualify through SSI or SSDI," Lange said. "For families who have assumed the ten-year rule was unavoidable, the chronically ill exception could completely change the planning conversation."
The webinar includes a session by Hook on who may qualify and how certification works, a session by Lange on the disclaim-to-special-needs-trust strategy, a live question-and-answer session, and a closing session on Roth IRA conversions. Understanding the strategy early can be critical, the organizers said, because beneficiary designations and trust provisions often have to be coordinated before the IRA owner dies.
Attendees will receive two recent Forbes.com articles by Lange on the chronically ill pathway, Hook's Chronically Ill EDB Planning Guide & Certification Template Package, a digital reprint of Lange's Forbes article on the disclaim strategy, and a complimentary hardcover copy of Retire Secure for Parents of a Child with a Disability while supplies last.
The program is intended for parents and grandparents of a child or grandchild with a disability or a condition that limits independent living. Registration is free at DisabledChildPlanning.com/Parents. The webinar runs from 10 a.m. to 1 p.m. Eastern on Sept. 2.
Drafted by a large language model from the source reporting linked above, then screened by automated publishing checks. It is not read by a journalist before publication. Some articles cite our Alpha Score. Verify prices and figures against the original source. Educational coverage, not personalized advice.